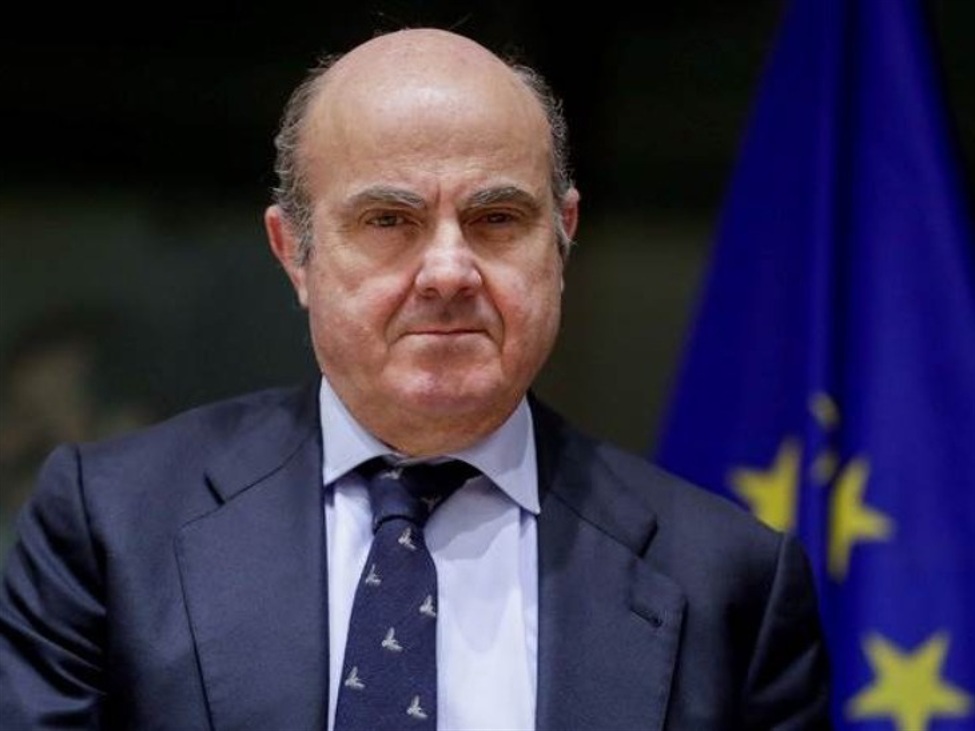
I think the inflation risk is lower this time aroundI think that we were late to act in 2021 and 2022One reason was that we had too much of an academic discussion about the drivers of inflationAcademic discussions are good at university and in academic fora but in central banking, you have to take decisionsWe have to wait before deciding on the next interest rate moveNeed more clarity about the conflict in IranMy impression is that the data on growth over the coming weeks are not going to be goodEnergy shock is usually reflected in inflation indicators much more rapidly than in growth indicatorsThat’s why I would call for prudence, we need additional clarity with respect to the conflictI have never tried to pre-empt the rate decisionLet’s see the data over the coming weeks, let’s see the projections, let’s see what happens with the conflictMarkets’ response has been quite calm and that is a positive thingA big repricing in asset markets would have been very detrimental, amplifying the impact of the energy shockFiscal space is quite limited in the euro area at a time when we need to increase defence spendingOverlooking this risk would be a mistakeFull transcript
As a reminder, de Guindos will be seeing his term end at the end of this month. So, he can be a bit more bold with his commentary as is the case with all policymakers when they are set to depart from the central bank.
So far, he’s not saying too much though but is preaching patience and being more prudent. But in the bigger picture, I’m sure he knows very well too that the ECB cannot sit by idly for too long amid the shock to the inflation outlook.