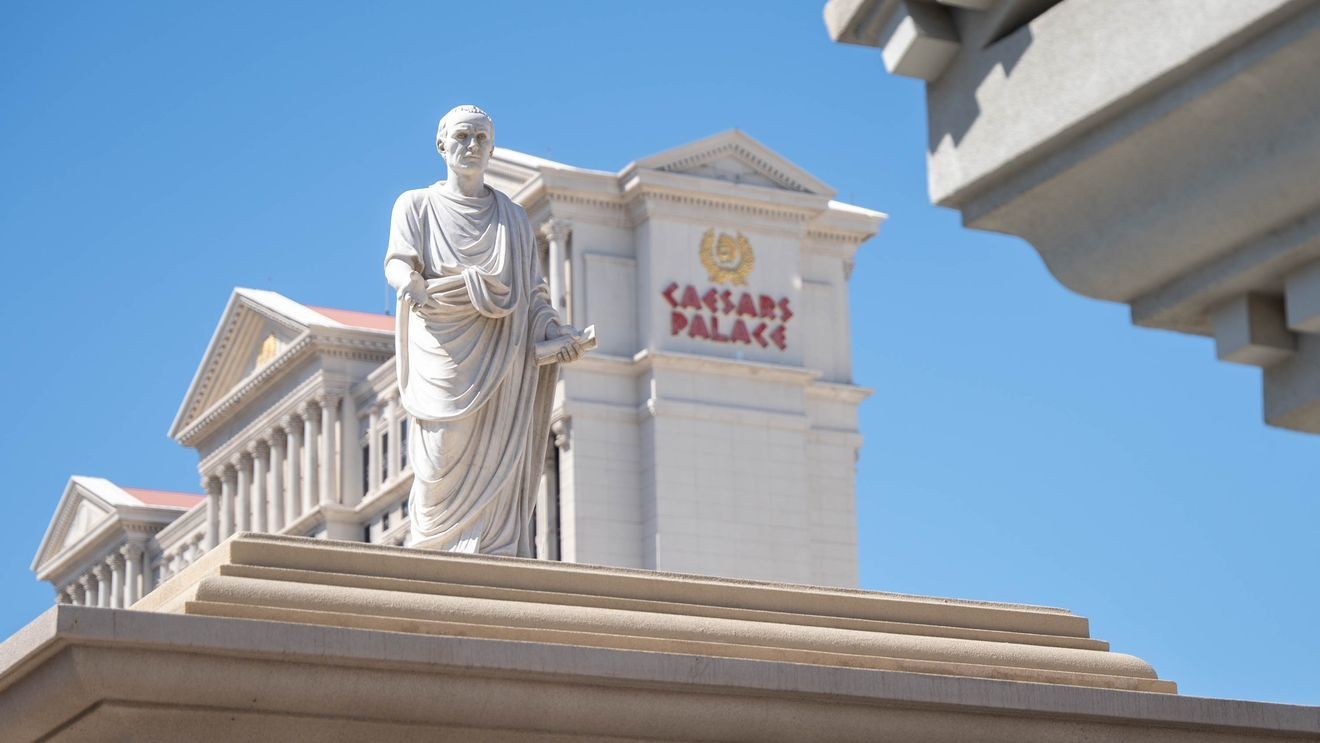
LAS VEGAS (KSNV) — Billionaire Tilman Fertitta’s company is buying out Nevada-based Caesars Entertainment for nearly $6 billion in cash.
Caesars Entertainment announced Thursday that it has agreed to be acquired by Fertitta Entertainment in an all-cash deal valued at about $17.6 billion, including the assumption of about $11.9 billion in Caesars’ outstanding debt.
Under the definitive agreement, Caesars shareholders would receive $31 in cash for each outstanding share.
The company said that the price represents a 49% premium over Caesars’ unaffected share price as of Feb. 25, 2026 — the last trading day before rumors of a potential transaction — and a 46% premium over the unaffected 30-day volume-weighted average price as of the same date.
Caesars’ board of directors approved the transaction and is recommending that shareholders adopt and approve the merger agreement.
It’s the latest shakeup for the company known as Caesars. The deal comes about six years after Reno-based Eldorado Resorts bought out what was then Caesars Entertainment Corporation in 2020 and adopted the latter’s name.
The Financial Times first reported in February that Caesars was considering takeover offers. Executives did not discuss the matter during a quarterly earnings call last month.
The company said the board, after consideration with outside financial and legal advisors, determined that the immediate cash premium offered is compelling for shareholders.
Fertitta Entertainment oversees the Golden Nugget chain of casino-hotels, which includes three locations in Nevada. Tilman Fertitta, who is currently the U.S. ambassador to Italy, also owns a major equity stake in Wynn Resorts.
Caesars said its CEO, Tom Reeg, CFO Bret Yunker, President and COO Anthony Carano, and other members of the corporate management team and property-level management and personnel are expected to remain in their roles and continue leading Caesars’ operations at the combined company.
The combined company would bring together Caesars’ casino and digital gaming business with Fertitta Entertainment’s hospitality and restaurant operations. Caesars said that, on a combined basis, offerings would include 60 casino resorts and gaming facilities; online gaming, including sports betting, iCasino and poker through Caesars’ digital platform; retail sports betting at more than 200 third-party locations through the William Hill brand; and more than 600 Fertitta Entertainment outlets, including Landry’s full-service restaurants, along with multiple amusement, entertainment, and aquarium venues.
The companies said the offerings would be connected by the Caesars Rewards loyalty network.
Culinary Union Secretary-Treasurer Ted Pappageorge said in a statement that he expects more discussions about how the buyout could affect workers, but was confident that union leaders would have a strong relationship with both Caesars and Fertitta.
“Culinary Union remains committed to ensuring that workers’ rights are respected, their jobs are protected, and the union contract is fully enforced,” Pappageorge said.
The proposed transaction is not subject to a financing condition. Caesars said the deal will be financed through a combination of equity contributed by Fertitta Entertainment, assumed Caesars debt, and new committed debt financing arranged by a group of 10 banks.
The transaction still requires approval from Caesars shareholders and must meet customary closing conditions, including regulatory approvals.
Caesars also said the Carano family, which owns about 5% of Caesars Entertainment common stock, has agreed to roll a portion of its equity interests into Fertitta Entertainment. After the deal closes, Caesars common stock will no longer be listed on NASDAQ.
The agreement includes a go-shop period through July 11, 2026, during which Caesars and its financial and legal advisors may solicit, consider, and negotiate alternative acquisition proposals from third parties.