Yet another week of wavering vibes was capped off last week by action as a surprising jobs report reset expectations for the October Fed meeting.
Even though the mere 29,000 jobs added in September made for a “miss,” the market celebrated what that meant: The labor market is definitely not overheating.
After Friday’s gains for the stock market, the S&P 500 once again finished about where it had started the week as market forces continue to cancel each other out.
7,755.07 +32.35 (+0.42%)
As of 10:27:59 AM EDT. Market Open.
^GSPC ^DJI ^IXIC
With a big week of jobs data behind us, the calendar of regularly scheduled programming will continue but leave plenty of space for organic news to grab the reins.
Taking point on the earnings calendar will be Tuesday’s beverage production and distribution giant, Constellation Brands (STZ), followed by another check on the food & beverage business with PepsiCo (PEP) earnings on Thursday. While it’s not often included in the discussion among AI’s biggest names, data center operator Applied Digital’s results will offer another check on the AI trade on Wednesday.
On the economic data front, the University of Michigan’s twice-monthly survey of consumer sentiment is likely to capture the largest share of attention after the last reading of the index showed sentiment fell to levels below those seen during the 2008 financial crisis.
A cool jobs report puts the Fed on hold, economists say
In an abrupt turnaround from August’s labor market outperformance, the US added just 29,000 jobs in September, missing expectations of 90,000, as the unemployment rate ticked up to 4.2%.
The release wasn’t necessarily bad, argue BNP Paribas US economists Andrew Husby and James Egelhof. It just wasn’t great.
“We see the broad trajectory of the US job market as positive, and consistent with our forecast of a gradually tightening trajectory we put in place in early June,” the economists wrote to clients.
September’s miss, economists say, points to a labor market that’s continuing to lose steam amid a long period of “low hire, low fire” dynamics. Average hourly earnings rose an anemic 0.1% from August and are up 3% year over year, a level that’s likely below the current rate of inflation.
What the jobs print is likely to do, though, is keep the Federal Reserve on hold in October. Odds of a 25 basis point hike at the FOMC’s October meeting have pulled back to roughly 20%, per CME data, as a not-steaming-hot labor market reduces pressure to hike immediately.
“We remain optimistic on economic growth and hiring, owing to still-stimulative policy and very well embedded economic optimism,” Husby and Egelhof wrote. “But that does not mean the Fed faces a hair-on-fire need to raise.”
Once again, economists say, CPI data — due next on Oct. 14 — is likely to be the swing factor for a final determination on where the Fed will go at its next meeting, as CPI reports have become more critical to the Fed than jobs numbers in a labor market that has looked relatively healthy.
In other words, inflation remains in the driver’s seat.
“It would now take a very strong CPI to make the October meeting live,” writes JPMorgan chief US economist Michael Feroli. “We continue to look for another hike at the December FOMC meeting, on the assumption that the September and October price reports show still-sticky trends in core inflation.”
But that won’t always be the case, argues Rick Rieder, BlackRock’s chief investment officer of global fixed income. Even if one side is taking the reins right now, it bears remembering that the Fed’s mandate is a dual one: price stability and maximum employment.
“Employment is now the weak sister of data releases for the Fed, next to current readings on inflation,” Rieder said. “Yet, that condition won’t be a permanent one, and the underlying trends for both will bear watching over the coming months and quarters.”
 A now hiring sign is posted in the window of a Chipotle restaurant on June 05, 2026 in Los Angeles, California. (Justin Sullivan/Getty Images) · Justin Sullivan via Getty Images The American consumer’s mood is souring
Overall consumer spending has mostly held up throughout the last few months, powered by a muscular stock market that has magnified household wealth.
But that doesn’t mean people are necessarily feeling great about the economy.
Consumer confidence plunged in September to its lowest reading since 2014, according to data from The Conference Board. The organization’s consumer confidence index dropped to 81.9 from the previous month’s reading of 88.6, per Conference Board data published Tuesday. Economists had been looking for a sharply higher reading of 89. And there’s a lot to be distressed about.
“Consumers’ write-in responses regarding factors affecting the economy were mostly pessimistic in September,” Dana Peterson, chief economist at the Conference Board, said in a statement. “References to prices, the high cost of goods and services, and oil and gas prices in particular, rose to new heights.”
That report, published last Tuesday, will put even greater focus on Friday’s consumer sentiment release from the University of Michigan, especially after the last U. Mich. report saw vibes fall to levels lower than those seen during the great financial crisis.
In that report, economists are looking for — wait for it — vibes to deteriorate even further, with topline sentiment expected to fall again to 48 from the last report’s reading of 48.1. For comparison, the levels seen during the financial crisis tracked around 55 to 60.
All of this sets up a two-faced dynamic for investors, the Federal Reserve, and a White House headed into midterm elections where affordability is set to be a leading issue. Yes: People are spending, the labor market is expanding, the economy is growing. No: How people feel isn’t getting any better.
A local shopper searches for meat products September 21, 2026 at the Market 32 supermarket in South Burlington. Vermont. Grocery prices continued to rise sharply in August and early September due to higher tariffs, energy costs, and supply chain issues. (Robert Nickelsberg/Getty Images) · Robert Nickelsberg via Getty Images The problem’s not crude. It’s diesel.
Seven months into the war in Iran that has thrown the global energy market into disarray, exports of crude oil have actually begun to normalize in the Persian Gulf, bringing some relief to global buyers.
While crude oil exports from the Persian Gulf region have returned to roughly 98% of their pre-war levels, refined product exports — of diesel, gasoline, and other derivatives — have recovered only to roughly 3 million barrels per day, or about 58% of their pre-war levels, per JPMorgan Chase.
That difference has put immense pressure on refined products pricing. In the US, diesel prices have climbed to an all-time high, averaging $6.41 per gallon on Wednesday, per AAA, and have moved similarly in the European market.
On Friday, European leaders from the G7 countries announced they’d release 100 million barrels of crude oil and diesel onto the open market over four months to alleviate the pressure, led by a “substantial diesel release” within 20 days from the G7 members and the bloc’s partners.
The announcement comes after several days of pressure from the Trump White House on European nations to release oil products from their national reserves, threatening a US diesel export ban if they didn’t agree to a release from their own stores.
With diesel’s direct relationship to consumer prices, keep refreshing that diesel chart.
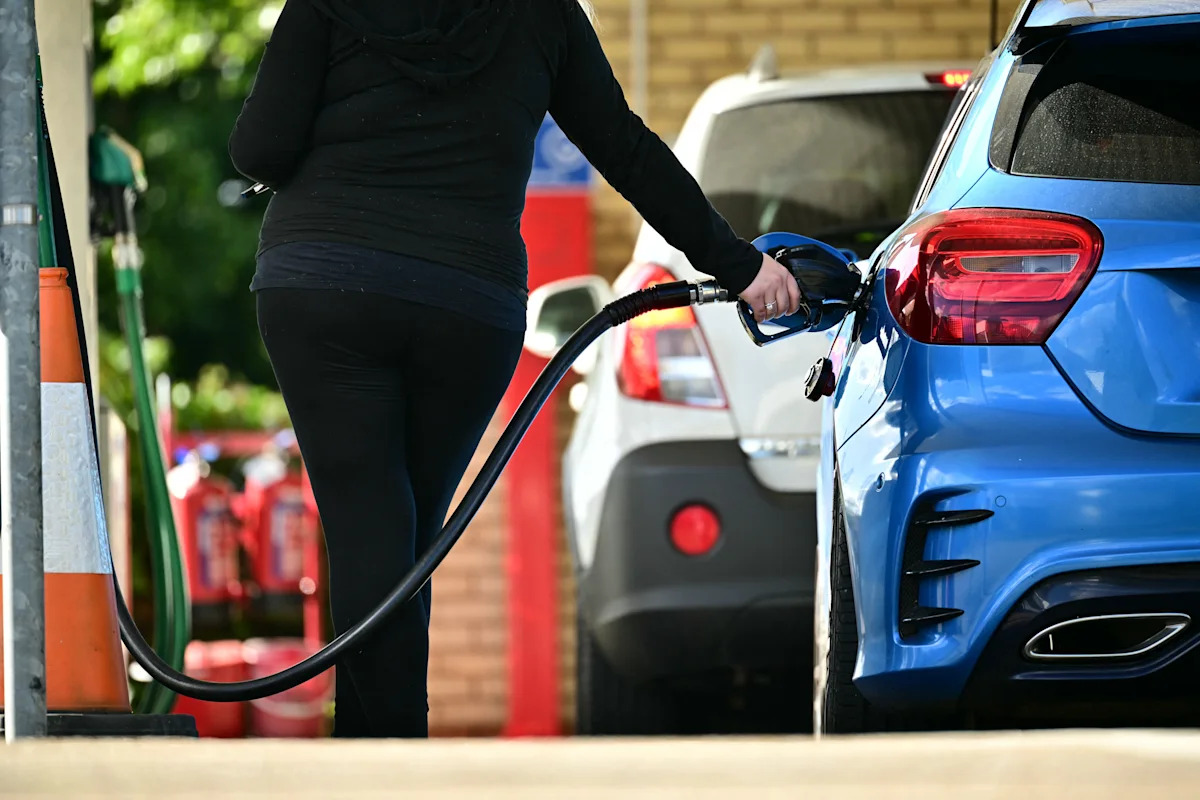
A motorist fills up a vehicle at a Tesco petrol station in Sevenoaks, south-east of London on October 2, 2026. The United States on October 1 told its European allies to help lower global diesel prices by releasing strategic reserves “immediately,” with EU member states due to discuss the crisis on Friday. (Ben STANSALL / AFP via Getty Images) · BEN STANSALL via Getty Images Economic and earnings calendar Monday
Economic data: S&P Global US services PMI, September final reading (58.7 expected, 58.7 prior); S&P Global US composite PMI, September final reading (58.4 prior); ISM services index, September (55.2 expected, 55.4 prior); ISM services, prices paid, September (73 expected, 72.6 prior); ISM services, new orders, September (73 expected, 72.6 prior); ISM services, new orders, September (60.5 expected, 60.9 prior); ISM services, employment, September (49 expected, 47.8 prior)
Earnings calendar: No notable earnings.
Tuesday
Economic data: ADP weekly employment change, week ended Sept. 19 (20,000 prior); Trade balance, August (-$89.8 billion expected, -$88.6 billion prior); Imports, month-on-month, August (+2.8% prior); Exports, month-on-month, August (-2.1% prior)
Earnings calendar: Constellation Brands (STZ), RPM International (RPM), Lamb Weston Holdings (LW)
Wednesday
Economic data: MBA mortgage applications, week ended Oct. 2 (-6% prior); NY Fed 1-year inflation expectations, September (+3.64% expected, +3.58% prior); FOMC meeting minutes, Sept. 16 meeting
Earnings calendar: Levi Strauss & Co. (LEVI), Applied Digital (APLD)
Thursday
Economic data: Initial jobless claims, week ended Oct. 3 (197,000 prior); Continuing claims, week ended Sept. 26 (1.701 million prior); Wholesale inventories, month-on-month, August final reading (+0.7% prior)
Earnings calendar: PepsiCo (PEP)
Friday
Economic data: U. Mich. sentiment, October preliminary reading (48 expected, 48.1 prior); U. Mich. current conditions, October preliminary reading (50.9 prior); U. Mich. current expectations, October preliminary reading (46.3 prior); U. Mich. 1-year inflation, October preliminary reading (+4.6% prior); U. Mich. 5-10 year inflation, October preliminary reading (+3.4% prior)
Earnings calendar: Delta Air Lines (DAL)
Click here for in-depth analysis of the latest stock market news and events moving stock prices
Read the latest financial and business news from Yahoo Finance